
Greenlight: For Families
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Greenlight: For Families - Screenshots
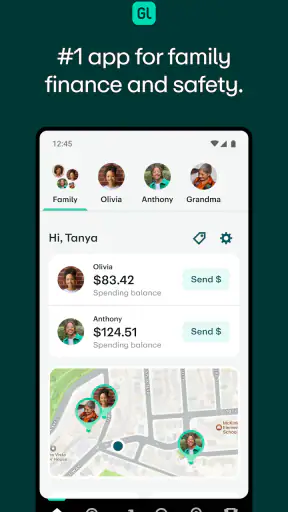
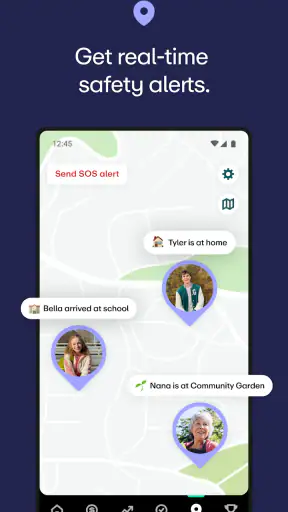
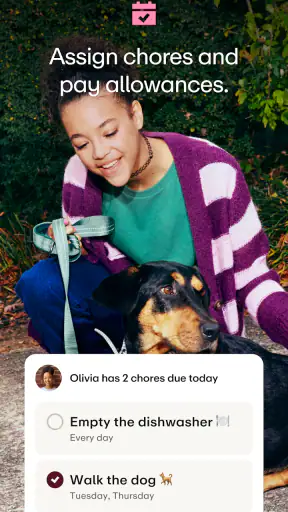
Pros
- Parents can manage spending limits and approve purchases in real time.
- Kids can learn budgeting through a dedicated debit card and app experience.
- Instant transaction notifications help families monitor account activity.
- The app supports chore payments and recurring allowances.
- Parental controls make it easy to pause or lock a child’s card.
Cons
- A monthly subscription may be expensive for families with several children.
- Availability and features can vary depending on the user’s location.
- Some card and ATM transactions may involve additional fees.
- Children need parental guidance to understand responsible spending.
- Account setup requires personal and financial information from the parent.
Greenlight: For Families - Description
- App Name
- Greenlight: For Families
- Package Name
- me.greenlight
- Developer
- Greenlight Financial Technology, Inc.
- Category
- Finance
- Last Updated
- Dec 23, 2016
- Version
- 8.6.0
Managing a child’s first spending card can feel like a bigger decision than it should. I found that Greenlight: For Families is designed to make that transition more visible and more structured, with the parent using the app while the child or teen uses the connected debit card. It is a finance app from Greenlight Financial Technology, Inc., aimed at families who want children to practice spending with adult oversight rather than using an ordinary bank card without guidance.
The basic appeal is easy to understand: I can treat everyday spending as a learning opportunity while still keeping the parent in the driver’s seat. That makes it different from a standard banking app intended for one adult managing personal money. It also feels more purposeful than simply handing over cash, because the parent and child can discuss where money goes, when it is available, and what responsible spending looks like.
Greenlight is free to install and is rated for Everyone, which makes the app approachable for a household with children at different stages. It has reached over a million installs and holds a 4.7 average from around 86 thousand ratings, so it is clearly familiar to many families. I would still treat those figures as a sign of broad adoption, not as a guarantee that its approach will suit every household.
What to expect before handing over the card
The first thing to understand is that this is not simply a child-facing wallet. The parent’s app experience is central. The child gets a spending tool, but the adult gets the structure around it. That distinction matters because the value comes less from the physical card alone and more from the conversations and routines built around it.
I would expect the app to work best when the family agrees on a simple purpose before setup. Is the card mainly for school lunches, occasional treats, planned purchases, or learning how to manage an allowance? Without that conversation, the app can become another place where a parent says yes or no to transactions without teaching much about money.
For a first-time user, the most reassuring part is the clear division of responsibility. The adult should begin with the parent account and household rules, while the child should learn what the card is for and how to check before spending. That prevents the common mistake of treating the card like unlimited money just because it looks and works like a normal debit card.
The app belongs in the family-finance category, but I would not compare it directly with a full banking app for adults. A traditional bank account may be better if your priority is salary payments, bill management, savings products, or a broad set of adult financial services. Greenlight’s strength is narrower and more practical: giving children a controlled way to use money while parents remain involved.
It is also worth setting expectations about independence. A teenager who wants complete privacy and unrestricted control may find the parent-managed model frustrating. That is not a flaw in the concept; it is the point of the product. I would choose it for supervised learning, not for recreating an adult account with none of the family oversight.
Who will get the most from it
I think the best match is a parent who wants to move beyond handing out cash but is not ready to remove all guidance. It can fit a child who is beginning to make small purchases, a teenager learning to plan spending, or a family trying to make allowance discussions more concrete.
It is especially useful when money lessons need to happen in ordinary moments. A child can think about whether a snack is worth buying now, whether to save for a larger item, or whether a planned purchase fits the amount available. Those decisions are more memorable than a lecture about budgeting.
I would be more cautious if the family rarely checks the app or does not want to discuss spending. A managed card still needs active parenting. It should not be treated as an automatic substitute for explaining needs, wants, saving, and consequences.
Getting through the first setup without confusion
After installing the app, I would start slowly rather than rushing to put the card into a child’s hands. The parent should first become comfortable with the main account view and understand where family-level decisions are made. The exact screens can change as the app develops, but the principle remains the same: learn the adult side before asking a child to use the child side.
Greenlight’s current version is 8.6.0, and the app requires operating system version 10 or later. That requirement is easy to overlook when a family uses an older phone or a hand-me-down device. I would check the device before beginning, especially if the child is expected to use the app independently. A card may be ready, but an incompatible phone can interrupt the first experience.
During setup, keep the first goal modest. Do not try to create a complete financial education system in one sitting. Decide what the first spending purpose will be, explain the rule in plain language, and make sure both parent and child know how to identify the available balance before making a purchase.
A useful approach is to establish one repeatable routine: the child checks the balance before spending, makes the purchase, and then reviews what happened afterward. That small loop teaches more than a long list of rules. It also gives the parent a chance to ask what the child intended to buy, whether the purchase was planned, and how much remains.
Another practical tip is to separate “permission” from “awareness.” A parent may want to approve certain types of spending, while other small purchases may simply need to be visible. If every purchase requires a conversation, the system can become tiring. If nothing is discussed, the learning opportunity disappears. I would begin with a clear boundary for larger or unusual purchases and leave ordinary low-stakes decisions as practice.
Before the first real transaction, I would also explain that a debit card spends available money rather than creating a borrowing balance. That distinction is important for children who have seen adults use credit cards. The app can support a controlled learning environment, but the child still needs to understand that the amount available is limited and that a declined purchase is not a technical puzzle to work around.
The first successful action should be deliberately boring
For a first meaningful success, I would choose a small, familiar purchase rather than an exciting one. A school snack, a simple activity, or another ordinary item gives the child a clear before-and-after example. The parent can check the available balance first, let the child make the decision, and then review the result together.
This is where the product starts to feel different from cash. With cash, the child may know what is left by counting it, but the parent may not see the same picture. With Greenlight, the family can use the app as a shared reference point. The child learns to look before spending, and the parent can focus on the decision rather than guessing what happened.
I would avoid turning that first purchase into a test. If the child makes a reasonable choice, the success is not merely that the transaction works. The real success is that the child can explain the choice and understand its effect on future spending.
A helpful follow-up is to ask three simple questions: What did you plan to buy? What do you have left? What might you choose next? These questions keep the conversation practical and avoid making the app feel like a monitoring tool. They also help reveal whether the child understands the balance or is simply tapping a card and hoping it works.
For a teenager, the first success might be slightly more advanced: planning several small expenses over a week instead of spending everything immediately. In that situation, I would encourage the teenager to estimate upcoming needs before using the card. The parent can then discuss the plan afterward without taking over every decision.
Where new users commonly get confused
The biggest confusion is often about who the app is really for. Children may assume it is their banking app, while parents may assume the card alone will teach good habits. In practice, the adult controls the framework and the child practices within it. Both sides need to understand that relationship from the beginning.
Another source of friction is the difference between a visible transaction and a completed lesson. Seeing a purchase in the app tells the parent what happened, but it does not explain why the child made the choice. I would use transaction visibility as a prompt for a calm conversation, not as a reason to interrogate every item.
Families can also become confused when they set rules that are too complicated. Multiple exceptions, changing expectations, and unclear allowance timing make it hard for a child to know what the card represents. I recommend starting with one spending purpose and one review habit. Once that feels natural, add another responsibility.
There can be a temptation to use the app mainly for control. That may work briefly, but it can weaken the child’s sense of ownership. I found the balance better when the parent explains the reason behind a boundary and lets the child make safe choices inside it. The app is more valuable as a practice space than as a constant approval queue.
Parents should also remember that a debit card is not a replacement for emergency planning. A child should know what to do if a purchase is declined, the card is misplaced, or the phone is unavailable. Those conversations are not glamorous, but they prevent panic and make the first independent outings safer and more predictable.
How it compares with cash, a bank account, and payment apps
Cash remains the simplest alternative. It is tangible, easy to understand, and does not require a device. For a young child learning basic counting, cash may actually be better at first. The trade-off is that cash is harder for parents to observe, easier to lose, and less convenient for purchases that expect a card.
A regular bank account can offer a more conventional financial relationship and may be the better long-term choice for an older teenager who needs broader banking services. However, an adult account can feel too advanced or too detached from family teaching. Greenlight is more focused on the stage where supervised practice matters.
General payment apps may be convenient for sending money, but convenience is not the same as a family learning framework. If your main need is to transfer money quickly to an older child who already manages spending responsibly, a simpler transfer tool may be less effort. If your goal is to make spending visible and discuss it, the parent-managed structure here is more relevant.
The trade-off is that Greenlight asks the family to participate. That extra structure is its reason for existing, but it also creates work. Parents who want a set-and-forget solution may become disappointed, while parents who want a bridge between allowance and independent spending may find the involvement worthwhile.
Practical routines that make the app more useful
I would connect the card to a weekly money conversation rather than checking it randomly. The conversation can be brief: review recent spending, identify one good decision, and choose one thing to plan for next. This keeps the app from becoming associated only with correction.
For younger users, use concrete categories such as school food, outings, and personal treats. For teenagers, shift the language toward planning, trade-offs, and timing. The same card can support different levels of responsibility, but the parent should adjust the conversation as the child becomes more capable.
One non-obvious benefit is that the app can make invisible spending visible enough to discuss without relying on memory. A child may sincerely believe that several small purchases “barely count.” Looking back at the activity can show how repeated choices affect the remaining balance. That is a more useful lesson than simply saying the child spends too much.
Another useful trade-off is deciding when to let a mistake stand. If a child spends money intended for a later treat, immediately replacing it may erase the consequence. I would usually let the child experience the planning result, provided the purchase was safe and within the agreed boundary. The parent can help create a better plan next time without turning one mistake into a punishment.
For shared family use, keep the rules consistent between adults. If one parent treats the card as a learning tool and another reverses every uncomfortable purchase, the child receives mixed signals. The app cannot solve that disagreement; the family needs to settle the basic expectations first.
Who should skip it, and what to do next
I would skip Greenlight if you do not want a parent-managed card, if your child is not ready to understand limited funds, or if your household already has a financial system that works smoothly. More features and more visibility are not automatically better when they add another routine to an already busy family.
I would also look elsewhere if your main requirement is adult banking rather than supervised child spending. The app is not the right center for a household seeking comprehensive personal finance management. Its value is concentrated in the parent-child learning relationship.
For everyone else, the next step after setup is not adding more rules. It is completing one ordinary purchase and reviewing it calmly. Once that works, choose a recurring moment for checking the balance and talking about the next decision. That path gives the child a sense of progress while keeping the parent involved enough to prevent avoidable surprises.
Greenlight: For Families has been available since December 23, 2016, and its continued presence in the finance category reflects a clear use case: helping families introduce card spending with adult management around it. I like the idea because it turns money into something a child can practice, not just something a parent can hand over.
My final view is positive, with one important condition: the family has to use the app as part of a conversation, not as a substitute for one. The free price makes trying it less intimidating, and the Everyone age rating keeps the product approachable, but the real question is whether your household wants this kind of guided independence. If the answer is yes, it offers a practical first step from cash allowance toward responsible card use. If the answer is no, a simpler cash routine or a conventional account may be a better fit.
FAQ
What is Greenlight: For Families?
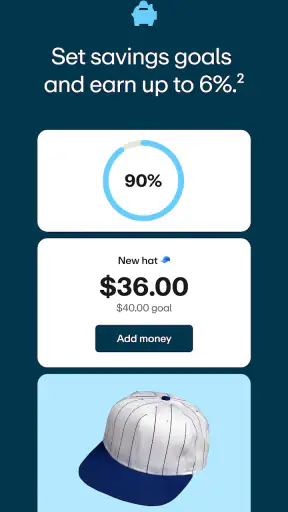
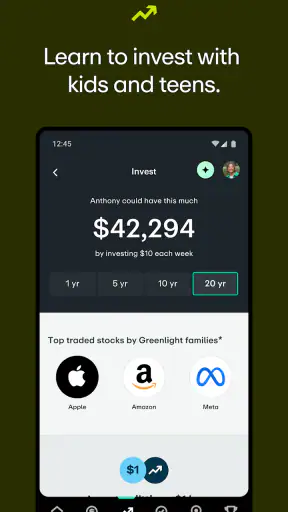
Greenlight: For Families is a family-focused money management app designed to help parents teach children and teenagers about spending, saving, earning, and responsible financial habits. Parents generally manage the family account from their own device, while children use a companion experience to view their available money, track purchases, set savings goals, and learn through everyday financial decisions.
How does Greenlight: For Families work for parents and children?
The app gives parents oversight and control while providing children with age-appropriate access to money. Parents can typically add funds, review transactions, create spending rules, organize money into categories or goals, and receive purchase notifications. Children can check balances, monitor their activity, and practice budgeting. Available tools and permissions may vary depending on the selected plan and the child’s age.
Is Greenlight: For Families safe for children to use?
Greenlight: For Families is built around parental supervision, which can make it a useful way to introduce children to financial responsibility without giving them unrestricted control. Parents can monitor activity and establish limits, while children learn to make controlled spending choices. However, parents should still review transactions regularly, explain online safety, and discuss scams, privacy, and responsible card use.
Does Greenlight: For Families charge a subscription or other fees?
Greenlight: For Families may require a recurring subscription, and the price can depend on the plan selected, the number of included features, and any current promotional offer. Additional charges may also apply for certain services, transactions, or optional benefits. Before downloading or subscribing, check the latest pricing, trial terms, renewal conditions, and cancellation policy shown in the official app store or Greenlight’s website.
What devices and accounts are required to use Greenlight: For Families?
To use Greenlight: For Families, a parent or legal guardian normally needs a compatible Android or iOS device, an internet connection, and an account that satisfies the service’s eligibility and identity requirements. Children may use a separate app experience or linked account, depending on the current product setup. Compatibility, location availability, age rules, and required verification can change, so confirm the latest requirements before signing up.


